Quick answer
Melbourne businesses can borrow $20k to $5m against property or use unsecured options for trading businesses. Victoria's payroll tax threshold is $1 million from 1 July 2025, with the deduction phasing out between $3 million and $5 million. Commercial and industrial property bought from 1 July 2024 enters the state's reform away from stamp duty. The Victorian Small Business Commission provides low-cost help with retail lease disputes.
Key points
- Victoria's payroll tax threshold is $1m, the joint-lowest of any state
- Warehouses and factories now enter the CIPT reform on their first qualifying sale
- Melbourne's west and south-east industrial belts drive equipment and premises finance
- Retail and hospitality tenants can use the VSBC for lease disputes
- Payroll tax threshold
- $1m (VIC)
- Commercial property
- CIPT reform
- Secured loans
- $20k – $5m
- Lease disputes
- VSBC
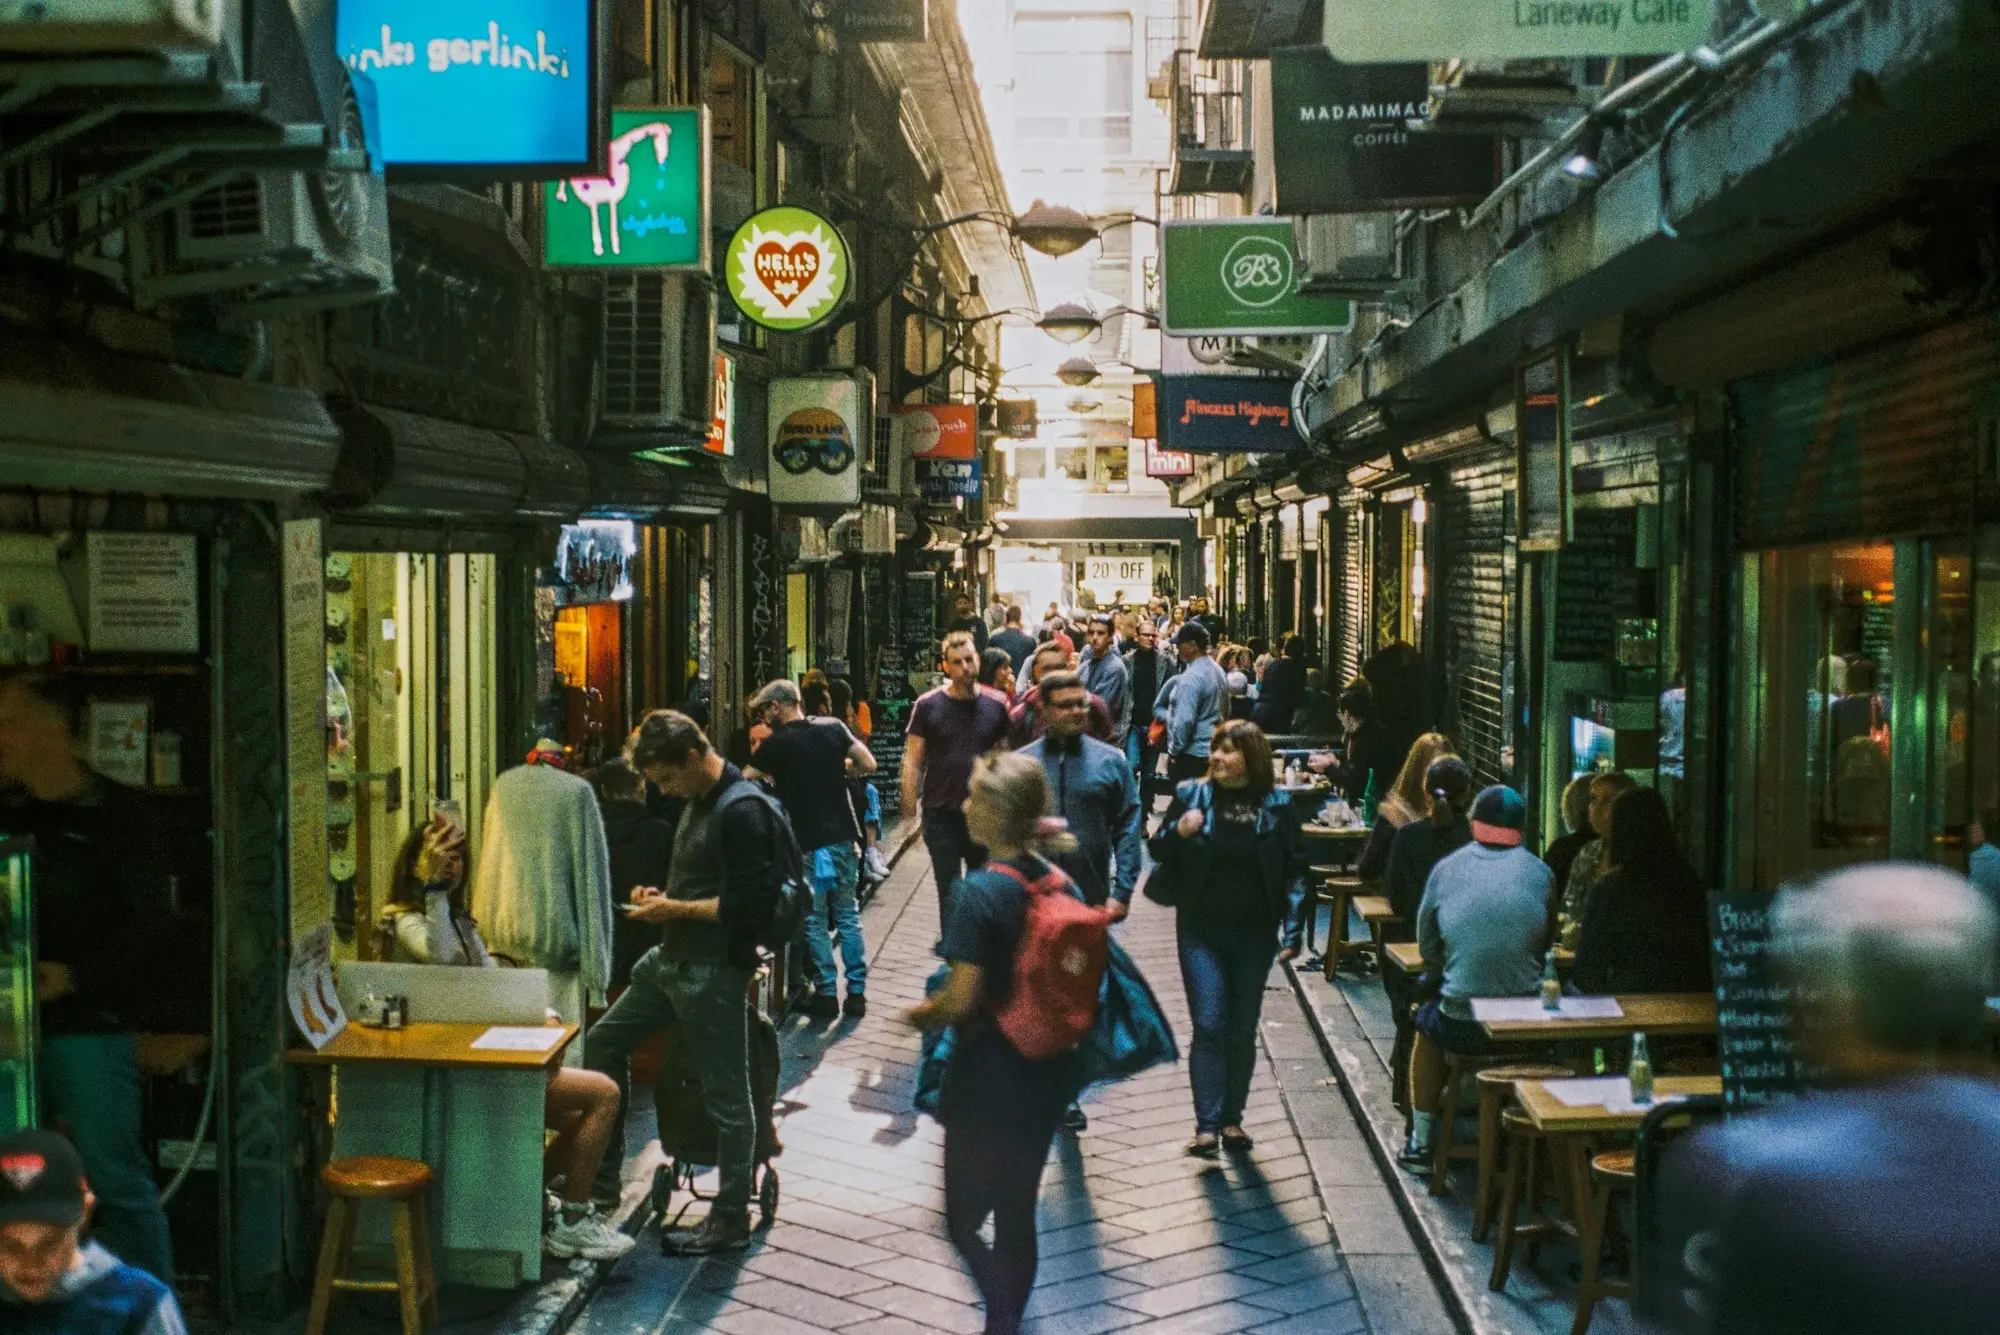
Melbourne has the bones of a manufacturing city and the soul of a hospitality one. Its industrial belts in the west and south-east make and move a lot of what the country buys, while its laneways, strips and suburbs are packed with cafés, clinics, studios and trades. For business owners, two Victorian changes stand out: the payroll tax threshold went up in 2025, and buying commercial or industrial property now works differently.
Where does Melbourne’s business activity sit?
- The CBD, Southbank and Docklands — professional services, tech, education and the hospitality that surrounds them.
- The west — Laverton, Truganina, Derrimut and surrounding estates, home to logistics, warehousing and food processing.
- The south-east — Dandenong, Braeside, Clayton and beyond, with deep roots in manufacturing, engineering and trade suppliers.
- The northern and western growth corridors — Wyndham, Melton, Hume and Whittlesea, pulling in trades, childcare, allied health and franchised services as new suburbs fill.
- Inner-ring strips — Fitzroy, Brunswick, Richmond, South Yarra and many more, dense with independent retail and food businesses.
What should Melbourne owners know about Victorian tax?
Payroll tax
The threshold is $1 million from 1 July 2025, up from $900,000. The deduction shrinks as Australian wages move from $3 million to $5 million, and disappears at $5 million. Melbourne businesses pay the general rate; the lower regional rate is only for businesses based in regional Victoria with at least 85% of wages paid there. If you’re weighing a second site in Geelong, Ballarat or Bendigo, that difference is worth modelling; the Geelong page covers it.
Buying premises under the CIPT reform
Victoria is shifting commercial and industrial property away from stamp duty. From 1 July 2024, a qualifying property enters the reform on its first sale. Duty is paid one last time on that sale, or financed through an optional government transition loan repaid over 10 years. Ten years after entry, the property starts paying an annual Commercial and Industrial Property Tax, and later sales don’t attract duty.
For a Melbourne business buying a warehouse or factory, the practical questions are:
- Has this property already entered the reform? If so, you may pay no duty on your purchase.
- If it hasn’t, will you pay the duty upfront, finance it within your business loan, or use the transition loan?
- How will the future annual tax affect your holding costs?
Our stamp duty comparison sets Victoria’s approach beside the other states.
How do lenders view Melbourne property?
Melbourne homes, units, warehouses, factories and shops are widely accepted as security. As in Sydney, the most common structure is a second mortgage behind an existing home loan, or a first mortgage over an investment or commercial property. Lenders will weigh the total debt against the property’s value, and some take a more careful view of small apartments or highly specialised buildings.
Borrowing against property covers anything from $20,000 to $5,000,000. For businesses without property, unsecured and cash-flow options typically run from $5,000 to $500,000, based on trading history and bank statements. Find out what your business could qualify for — enquiring won’t touch your credit file.
What local support can Melbourne businesses use?
- Business Victoria — grants and programs, advice and events. Rounds open and close, so check before you plan a big project.
- Victorian Small Business Commission — low-cost dispute resolution, including retail tenancy mediation. Melbourne’s hospitality and retail tenants use it often; see the small business commissioners guide.
- Local councils — many run small business grants, activation programs and advice sessions for their shopping strips.
Leasing in Melbourne: know your rights first
Many Melbourne businesses rent their premises, and the lease is often the biggest fixed cost they have. Before you sign or renew, check the rent review terms, the outgoings you’ll pay, who is responsible for repairs, and the make-good obligations at the end. If a dispute arises, the Victorian Small Business Commission is a low-cost first step. If you’re comparing leasing with buying, factor in the CIPT reform and land tax on one side, and rent increases on the other.
What do Melbourne owners borrow for?
| Need | Typical approach |
|---|---|
| Warehouse or factory purchase | Property-secured loan for deposit and duty; check CIPT status |
| Café, clinic or studio fit-out | Second mortgage or unsecured finance, depending on size and history |
| Stock and staff for peak season | Line of credit or short-term working capital |
| Payroll tax after fast growth | Working capital sized on turnover |
| ATO debt clean-up | Property-secured or unsecured, considered case by case |
Illustrative example: a Dandenong South engineering firm has rented the same factory for a decade. The owner is offered the chance to buy. The property hasn’t yet entered the CIPT reform, so the purchase will carry the final duty. The owner uses a property-secured business loan against the factory and a home in the eastern suburbs, and chooses to fund the duty within the loan rather than tie up working capital.
Start with a quick Melbourne enquiry
From Werribee to Warrandyte, it’s the same one-minute form: where you are, how much you need, what it’s for and whether there’s property to use. There’s no credit check to enquire. Your details aren’t hawked to a list of lenders — one team handles them, and a real person rings you to talk through the options. Please be accurate with your answers so we can match you properly from the start.
Frequently asked questions
Is it better to buy or rent a warehouse in Melbourne now?
It depends on your plans, but the CIPT reform changes the maths. A warehouse that has already entered the reform may not attract duty on your purchase, while one that hasn't will need the final duty paid or financed through the transition loan. Your conveyancer can check a property's status.
What payroll tax does a Melbourne business pay?
Victoria's threshold is $1 million a year from 1 July 2025. The deduction reduces for Australian wages between $3 million and $5 million. Melbourne businesses don't qualify for the regional rate, which is reserved for businesses based in regional Victoria.
Who can help with a retail lease dispute in Melbourne?
The Victorian Small Business Commission provides low-cost dispute resolution, including mediation for retail tenancy disputes, and issues certificates for leases shorter than five years.
Can I get a business loan in Melbourne without property?
Yes, if the business is trading. Unsecured and line-of-credit options, typically $5,000 to $500,000, are assessed on turnover and bank statements.
Can I borrow against an investment property for my business?
Usually. Residential investment property and commercial property can both be used as security for a business-purpose loan, subject to the lender's valuation and limits.